
Trust administration is the process of managing and distributing a trust after the creator dies or can no longer serve. In New Jersey, the successor trustee must notify beneficiaries, secure and value trust assets, pay debts and taxes, keep records, and distribute assets under the trust terms.
Unlike probate, trust administration usually happens without court appointment. Patrick Banks Law guides Bergen County trustees and beneficiaries through each step.
A living trust is often created to spare a family the time and publicity of probate. That goal is only reached if the trust is administered correctly after the person who created it passes away.

If you have been named successor trustee, you now hold a legal role with real responsibilities. This page explains what New Jersey expects of trustees and what beneficiaries can expect in return. For the full picture of settling a loved one’s affairs, see our overview of Bergen County estate administration .
What Is Trust Administration?
A trust is a legal arrangement in which one person, the trustee, holds and manages property for the benefit of others, the beneficiaries. The person who creates the trust is called the settlor or grantor.
Most families encounter trust administration after the death of a parent or spouse who had a revocable living trust. At death, the trust typically becomes irrevocable, and the successor trustee named in the document takes over.
From then on, the successor trustee must follow the trust’s instructions. Those instructions might call for distributing everything right away, or for holding assets in continuing trusts for years.
Trust Administration vs. Probate
Trust administration and probate share many tasks. The biggest difference is how involved the court is.
| Probate Administration | Trust Administration | |
|---|---|---|
| Who is in charge | Executor named in the will | Successor trustee named in the trust |
| Court appointment | Required through the County Surrogate | Generally not required |
| Public record | The will becomes a public record once probated | The trust document generally stays private |
| Authority to act | Letters testamentary | The trust document and a certification of trust |
| How long it lasts | Usually ends once the estate is distributed | Can end quickly or continue for years, depending on the trust terms |
| NJ inheritance tax | Applies to taxable transfers | Applies to taxable transfers |
One common surprise is that a trust controls only assets actually transferred into it. Accounts or property left in the deceased person’s individual name may still need to pass through probate. Our guide to the New Jersey probate process explains how that works.
New Jersey’s Trust Code and the Trustee’s Role
New Jersey adopted its version of the Uniform Trust Code in 2016. It sets default rules for how trusts are administered in the state, though many of those rules can be adjusted in the trust document.
The code, along with New Jersey’s Prudent Investor Act, requires trustees to follow core fiduciary duties:
- Administer the trust in good faith and according to its terms and purposes.
- Act with loyalty, solely in the beneficiaries’ interests.
- Treat beneficiaries impartially, giving due regard to their respective interests.
- Invest prudently, considering the trust’s purposes, terms, and the beneficiaries’ needs.
- Keep beneficiaries reasonably informed about the trust and its administration.
- Keep trust property separate and maintain adequate records.
These duties parallel an executor’s obligations during probate. Our page on executor duties and responsibilities explains how those responsibilities work on the probate side.
Step 1: Accept the Role and Gather Key Documents
Start by locating the original trust agreement and every amendment. Review it carefully to confirm you are the named successor trustee and to understand what it requires.
Gather certified death certificates, the deceased person’s will, recent account statements, deeds, and tax returns. These documents help you identify what the trust owns and what it owes.
If the trust names co-trustees, decide how you will work together. Many trust documents require co-trustees to act jointly on major decisions.
Step 2: Obtain an EIN and Secure Trust Assets
Once a revocable trust becomes irrevocable, it generally needs its own Employer Identification Number from the IRS. You will use that number to open trust accounts and file tax returns.
- Retitle accounts into your name as successor trustee.
- Confirm homeowners and other insurance remains in force.
- Secure real estate, vehicles, and valuable personal property.
- Keep trust funds completely separate from your own money.
Banks and brokerages usually ask for a certification of trust, which confirms the trust exists and that you have authority to act, without revealing every private detail of the document.
Step 3: Notify the Beneficiaries
Transparency is one of the most important parts of trust administration. Under New Jersey’s trust code, a trustee generally must notify qualified beneficiaries within 60 days after accepting the trusteeship, and within 60 days after a revocable trust becomes irrevocable.
The notice typically tells beneficiaries that the trust exists, who created it, who the trustee is, and that they have a right to request a copy of the trust terms and receive reports.
Prompt, clear communication does more than satisfy the law. It is also one of the best ways to prevent misunderstandings from becoming disputes.

Timeline is approximate and assumes outright distribution after death. Continuing trusts last longer.
Step 4: Inventory and Value Trust Assets
Create a complete inventory of everything the trust owns, along with date-of-death values. That can include bank and investment accounts, real estate, business interests, and personal property.
Accurate values matter for several reasons. They determine inheritance tax, set the tax basis for beneficiaries who later sell assets, and provide the starting point for your accounting.

For real estate, closely held businesses, and valuable collections, a qualified appraisal is often worth the cost.
Step 5: Pay Debts, Expenses, and Taxes
Before distributing trust assets, the trustee must address valid debts, administration expenses, and taxes. Depending on the situation, this can include:
- Final medical bills, funeral costs, and other valid debts
- The deceased person’s final federal and New Jersey income tax returns
- Federal and New Jersey fiduciary income tax returns for income the trust earns
- A New Jersey inheritance tax return, due eight months after death, when trust property passes to taxable beneficiaries
- A federal estate tax return for estates large enough to require one
New Jersey repealed its estate tax for deaths on or after January 1, 2018, but the inheritance tax still applies to trust assets just as it does to probate assets. Our page on New Jersey inheritance tax and estate tax explains the beneficiary classes and rates.
Financial institutions in New Jersey often hold back part of an account until the Division of Taxation issues a tax waiver. Planning for waivers early helps keep distributions on schedule.
Step 6: Manage and Invest Trust Property
A trustee must manage trust property as a prudent investor would. That means considering diversification, risk, the trust’s purpose, and the needs of current and future beneficiaries.
For a trust that distributes everything within a year, the focus is usually on preserving value. For a trust designed to last, such as a trust for a surviving spouse, a special needs beneficiary, or grandchildren, long-term investment strategy becomes central.
Trustees can generally hire investment advisors, accountants, and attorneys, and pay them from trust funds, as long as the fees are reasonable.
Step 7: Keep Records and Account to Beneficiaries
Record every receipt, expense, and distribution from the day you take over. Beneficiaries are generally entitled to reports showing the trust’s property, liabilities, receipts, and disbursements.
Most New Jersey trusts are settled through an informal accounting that beneficiaries review and approve. When disagreements arise, a trustee or beneficiary can ask the Superior Court, Chancery Division, Probate Part, to settle the accounts formally.
When a trustee fails to account or mismanages trust property, beneficiaries may pursue a claim for breach of fiduciary duty . Careful records are the trustee’s best protection.
Step 8: Distribute Assets and Close or Continue the Trust
Once the trustee handles debts and taxes, they distribute assets according to the trust terms. Some trusts call for outright distributions. Others direct the trustee to hold assets in separate continuing trusts.
When the trust ends, trustees commonly ask beneficiaries to sign receipts and releases, sometimes paired with refunding agreements, confirming what they received and protecting the trustee from later claims.
For continuing trusts, the trustee’s work goes on. That can include annual accountings, discretionary distribution decisions, tax filings, and ongoing communication for many years.
How Trustees Are Paid in New Jersey
A trustee is entitled to reasonable compensation. If the trust document sets the amount, that controls. If it does not, New Jersey statutes provide commissions based on the trust’s principal and income.
For corpus, the statutory commission is generally calculated each year at five-tenths of one percent of the first $400,000 of principal and three-tenths of one percent of the amount above that. A separate commission may apply to income the trust earns.
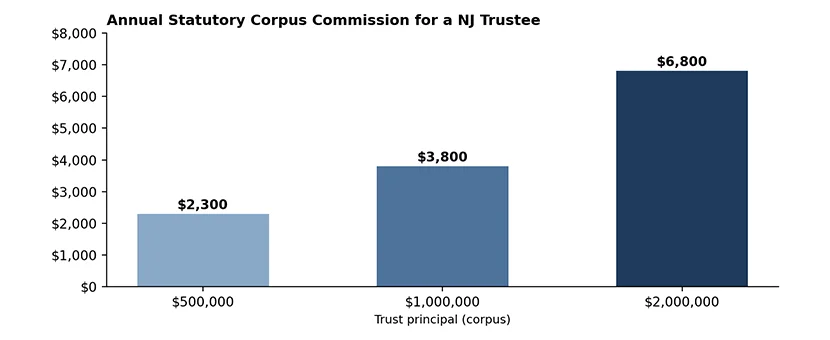
Calculated from New Jersey’s statutory trustee commission schedule for a single trustee. The trust document can set different compensation, and income commissions are not shown.
Many family trustees waive their commission, especially when they are also a beneficiary, because commissions are taxable income while distributions generally are not.
Common Trust Administration Mistakes
- Failing to send required notices to beneficiaries
- Distributing assets before debts, taxes, and waivers are resolved
- Mixing trust money with personal accounts
- Favoring one beneficiary over another
- Ignoring assets that were never transferred into the trust
- Leaving large sums uninvested for long periods
- Closing the trust without signed receipts and releases
Many of these problems start long before death, with a trust that was never fully funded. If you are reviewing your own plan, our page on revocable trusts explains how to make sure yours works as intended.
Just named successor trustee of a Bergen County trust? Attorney Patrick V. Banks has helped families administer trusts and estates throughout Bergen County since 2007. Call 201-483-2338 to schedule your free initial consultation.
Frequently Asked Questions About Trust Administration in New Jersey
What Happens When You Call Patrick Banks Law
When you call 201-483-2338, you will be asked to complete a short questionnaire about the trust, the assets involved, and where things stand today.
Attorney Banks then reviews your situation with you, whether you are a newly named trustee or a beneficiary with questions. Most calls end with a clear next step and a written fee quote.
Get Help Administering a Trust in Bergen County
Trust administration rewards careful, organized work, and small mistakes can create personal liability for the trustee. Patrick Banks Law helps trustees and beneficiaries in Ridgewood, Upper Saddle River, and throughout Bergen County, and our estate planning team can help you build a plan that makes administration easier for your own family.
Call 201-483-2338 or complete our online questionnaire to schedule your free initial consultation.
